Imagine a village built along the banks of a roaring, golden river. The water is thick with raw wealth, and the villagers spend their days scooping it into heavy buckets. But instead of drinking from it or using it to irrigate their crops, they load the buckets onto foreign boats. The boats sail away to a distant land, where the water is filtered, purified, and bottled. Months later, the boats return. The villagers, now parched and desperate, spend their life savings to buy back the very water they pulled from their own soil.
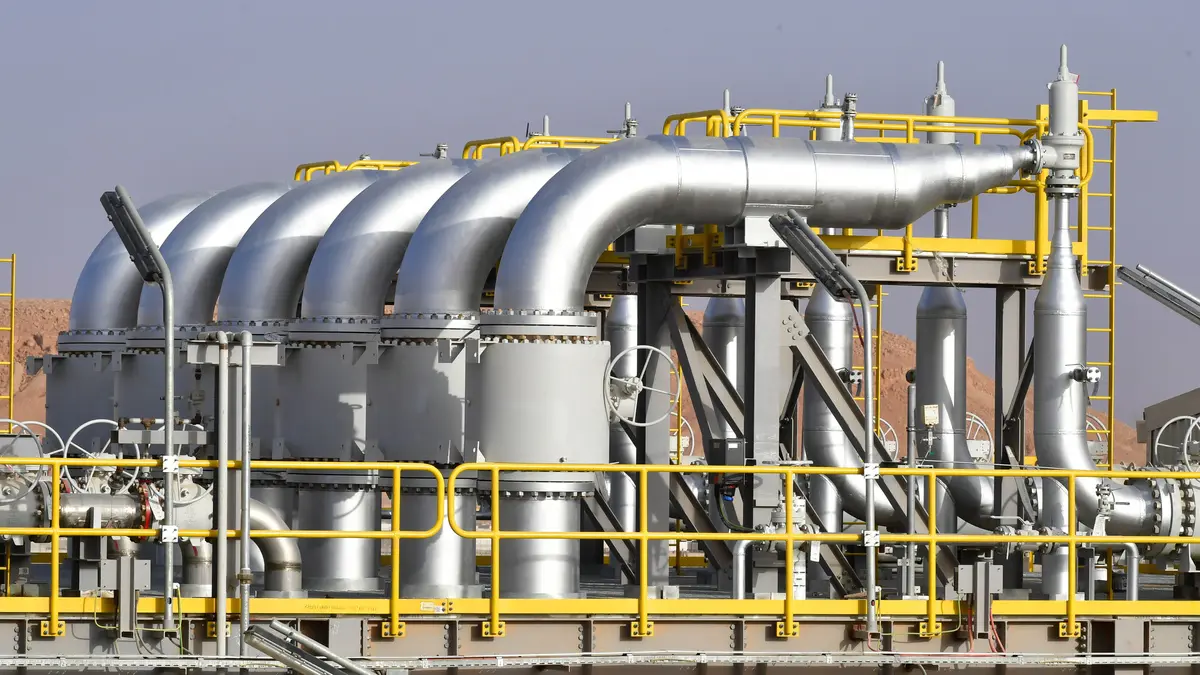
This is not a fairy tale. It is the living economic reality of Africa’s energy sector. The continent sits on roughly 125 billion barrels of proven crude oil reserves—about 12% of the world’s total—yet it remains entirely thirsty for refined fuel. Only about one-quarter of the crude oil extracted in Africa is refined locally. The continent generates over $190 billion in gross crude value annually, yet a massive portion of this wealth leaks into overseas markets through a broken import-export loop. By looking at global blueprints from nations like Saudi Arabia, Norway, and the UAE, Africa can map a unified path to maximum utilization, economic restructuring, and absolute sovereignty.
Part 1: Africa’s Refining Spectrum – Who Refines and Who Doesn’t
To understand why Africa is caught in this cycle, we must look at the infrastructure on the ground. The continent’s refining landscape is deeply fragmented, split between nations that can process their own wealth and those that are entirely dependent on foreign factories.
Tier 1: The Self-Refiners (Processing the Wealth)
These nations have successfully aligned their extraction with their industrial capacity. They understand the ancient truth: “The hunter who cooks his own game never begs for a meal.”
- Algeria (Skikda & Arzew Refineries): Operating Africa’s largest state-led footprint, Algeria’s 350,000 bpd Skikda facility and 90,000 bpd Arzew plant are entirely state-owned by Sonatrach. Algeria refines its own ultra-light Saharan Blend, fully satisfying domestic demand and exporting high-value petroleum products to Europe.
- Egypt (Mostorod, MIDOR, and Regional Clusters): Egypt operates a sophisticated web of 12 refineries managed by the Egyptian General Petroleum Corporation (EGPC). The MIDOR refinery (160,000 bpd) and the Mostorod complex process domestic crude and strategically imported regional grades, ensuring the Arab world’s most populous nation is an industrial refiner, not just an exporter.
- Libya (Zawiya & Ras Lanuf Refineries): Despite years of complex civil disruptions, Libya’s state-owned National Oil Corporation (NOC) keeps the Zawiya (120,000 bpd) and Ras Lanuf (220,000 bpd) refineries operational. They convert a steady portion of Libya’s sweet crude into domestic fuel, buffering the local economy from global price shocks.
Tier 2: The Paradox Titans (Rich in Crude, Poor in Fuel)
These nations pump millions of barrels of crude out of the ground but lack the functional capacity to refine it. They live out the warning: “A man who inherits a granary but loses the key will still starve.”
- Nigeria (The Turning Giant): Nigeria possesses four state-owned refineries—Port Harcourt (210,000 bpd), Warri (125,000 bpd), and Kaduna (110,000 bpd)—which have sat completely offline or operated at near-zero capacity for decades due to systemic mismanagement. This forced Nigeria to import over 80% of its petroleum. However, the narrative is shifting fundamentally. The private Dangote Petroleum Refinery (650,000 bpd) in Lekki is scaling rapidly, structurally flipping Nigeria from a helpless importer into a regional refining superpower.
- Angola (Luanda & Cabinda): As Africa’s second-largest crude producer, Angola historically exported almost 100% of its raw oil. Its state-owned Luanda Refinery (65,000 bpd), operated by Sonangol, satisfies less than 30% of domestic demand. Angola is actively deploying the Cabinda Refinery (30,000 bpd) with Gemcorp to try and stop the multibillion-dollar drain of importing foreign fuel.
- Ghana (Tema & Sentuo): Ghana presents a classic sub-Saharan paradox. The state-owned Tema Oil Refinery (45,000 bpd) has suffered prolonged operational halts. Meanwhile, the newly opened, private Chinese-Ghanaian Sentuo Oil Refinery (40,000 bpd) has begun processing domestic crude. Historically, Ghana actively exported nearly 100% of its high-grade domestic crude (like Jubilee and Tweneboa Enyenra Ntomme) while importing foreign finished products to run its economy.
- Central African Producers (Cameroon, Gabon, Congo): Facilities like Cameroon’s SONARA (42,000 bpd), Gabon’s SOGARA (21,000 bpd), and Congo’s CORAF (21,000 bpd) are small, state-partnered facilities. They are structurally incapable of processing the heavy, complex crude grades pumped locally, forcing these nations to sell raw oil cheap and buy finished fuel dear.
Tier 3: The Pure Importers (No Active Footprint)
These nations have either shut down their infrastructure or never built it, leaving them entirely vulnerable to global supply lines.
- East Africa (Kenya, Tanzania, Uganda): Since Kenya’s Mombasa Refinery was permanently shut down in 2013, East Africa has had zero active refining capacity. Uganda is developing its own oil fields and plans a domestic refinery, but for now, the entire region relies 100% on imported fuel.
- South Africa (Astron, SAPREF, Natref): South Africa once boasted a robust refining sector. However, the closure of SAPREF (180,000 bpd) and structural shifts have left only the Natref JV (108,000 bpd) and the Glencore-owned Astron Energy (100,000 bpd) operational. The country now imports the vast majority of its finished fuel.
Part 2: Changing the Narrative – The Financial Mechanics of Restructuring
For over sixty years, Africa has played the role of the world’s resource farm. To change this narrative, African states must realize that “wood already touched by fire is not hard to set alight.” The infrastructure, the resources, and the demand are already here; what is missing is strategic execution.
Historically, African nations have bled cash through an invisible macroeconomic wound: the currency loop. Under the old model, countries like Ghana and Angola exported raw crude to international markets to earn US Dollars, only to immediately spend those exact dollars—plus immense shipping, handling, and insurance premiums—to buy back finished fuel.
To heal this wound, aggressive structural shifts are being executed:
Old Broken Loop
New Clean Loop
1. Bypassing the US Dollar (Hard Currency Preservation)
Every time a domestic fuel supplier must buy refined petroleum from Europe, they must aggressively trade local currency for US Dollars, which weakens the local exchange rate and triggers fuel price spikes at the pump. By supplying domestic oil directly to local refineries, nations eliminate this foreign exchange pressure. In Ghana, scaling up local refining drastically reduces the demand for US Dollars, effectively insulating the Ghanaian Cedi from currency-driven inflation.
Ghana spends roughly $400 million every single month to import finished petroleum. Achieving 100% local refining self-sufficiency keeps $4.8 billion annually within the local banking sector, stabilizing national reserves. Maximizing this strategy across all African producers can keep an extra $110 billion annually on the continent.
2. Cutting the “Freight Premium” Losses
Importing fuel across oceans carries massive deadweight losses in shipping, maritime insurance, and offshore handling fees—averaging $20 to $30 per metric tonne. In a major milestone, Ghana’s Sentuo Oil Refinery took delivery of approximately one million barrels of crude from the domestic Jubilee Field for localized processing. This direct pipeline delivery bypasses international shippers entirely, saving hundreds of millions annually in raw freight overhead.
3. Eradicating Subsidies via Production (The Angola Model)
Angola historically spent up to $2 billion every six months importing refined fuel, prompting the government to heavily subsidize pump prices to protect citizens, which drained the national budget. Angola has launched sweeping downstream reforms and massive private-partnership builds. The new Cabinda Refinery (90% owned by investment firm Gemcorp and 10% by state oil firm Sonangol) went live, immediately taking over a growing portion of the domestic fuel supply footprint. By substituting expensive imports with cheaper, locally refined fuels, Angola is structurally eliminating the economic need for costly state subsidies without triggering widespread domestic inflation.
Part 3: Environmental and Technological Standards of Modern Mega-Refineries
A common criticism of expanding refining capacity in Africa is the environmental cost. However, Africa’s new era of mega-refineries is not duplicating the polluting, inefficient designs of the 1970s. Instead, they are integrating state-of-the-art technological standards that prioritize efficiency and emission reductions.
As the proverb reminds us: “The river flows forward, never backward.” African industrialization is skipping past old, dirty energy practices and moving straight toward cleaner tech.
1. Euro V and Euro VI Fuel Specifications
Older African refineries produced high-sulfur fuels that created heavy particulate emissions when burned in vehicles. Modern facilities like the Dangote Refinery in Nigeria and Angola’s phased Cabinda and Lobito expansions are built with highly advanced hydrocracking technology. These plants specialize in producing Euro V and Euro VI compliant fuels, which drop sulfur content to less than 10 parts per million (ppm). This clean-burning standard matches the strict environmental fuel mandates of Western Europe and North America, ensuring that localized energy does not mean localized pollution.
2. Closed-Loop Water Recycling and Effluent Treatment
Traditional refining consumes millions of gallons of water and risks contaminating local water tables. New-age facilities utilize highly integrated Effluent Treatment Plants (ETPs) and closed-loop cooling systems. Wastewater generated during the refining process is treated, purified, and cycled back into the facility for industrial reuse. This prevents harmful chemicals from spilling into local ecosystems and drastically minimizes the refinery’s freshwater draw from local communities.
3. Natural Gas Integration and Co-Generation Power
Historically, refineries burned heavy fuel oils to power their own internal operations, creating a massive carbon footprint. Modern African energy strategy relies heavily on natural gas co-generation. For example, Ghana has successfully shifted its thermal power and industrial systems from liquid fuels to domestically produced natural gas, saving $500 million in a single year. Mega-refineries use this domestic gas to run their internal boilers and power plants, cutting carbon dioxide emissions by up to 30% compared to traditional fuel-oil refining.
Part 4: Utilizing Refining Power for Continental Benefit via AfCFTA
True independence is not found in a national flag or an anthem; it is found in supply-chain sovereignty. When a continent refines its own energy, it controls its own destiny. As the proverb warns: “If you rely on another man’s horse, you will be left stranded in the middle of the journey.”
1. Unlocking the Industrial Value Chain (Petrochemicals)
Refining crude oil yields far more than just gasoline and diesel. It produces the essential raw materials for manufacturing: polypropylene for plastics, asphalt for roads, and sulfur and ammonia for agricultural fertilizers. Local refining will kickstart a manufacturing renaissance across Africa, allowing the continent to feed and industrialize itself.
2. The Infrastructure of the AfCFTA
The Dangote Group’s strategic acquisition of a 25% stake in Kenya’s petroleum pipeline network and its ongoing expansion into distribution hubs in Djibouti, Ethiopia, Cameroon, and Namibia serves as the perfect blueprint. Moving fuel through pipelines reduces distribution costs by up to 60% compared to road transport, making local African fuel highly competitive with imports from Europe or Asia. We must use the AfCFTA framework to build massive cross-border fuel corridors, allowing West and North African refining powerhouses to supply East and Southern Africa directly, bypassing foreign middlemen entirely.
Part 5: Human Capital and Local Workforce Training
Building advanced refineries is only half the battle; operating them requires a highly skilled local workforce. For decades, the African oil sector relied on expensive expatriate labor for specialized engineering roles. Today, an aggressive focus on local technical capacity is shifting the balance.
As the proverb reminds us: “Give a man a fish, and you feed him for a day; teach a man to fish, and you feed him for a lifetime.”
Modern mega-refineries require specialized expertise in chemical engineering, automation, and advanced fluid mechanics. In practice, operations at the Sentuo Oil Refinery and the state-backed downstream frameworks in Ghana rely on structured training partnerships with international institutions. These programs transition fresh African engineering graduates into hands-on operational roles through rigorous mentorship.
Similarly, during the construction and commissioning of the Dangote Refinery, thousands of young African engineers were sent to global training hubs to master complex refining technologies, establishing a deep pool of domestic talent. Investing in local workforce training keeps high-paying engineering and technical management salaries within the domestic economy. This technical workforce then forms the foundation for secondary industries, such as petrochemical manufacturing, plant maintenance, and industrial safety services, driving broad-based economic growth.
Part 6: Strategic Playbooks Africa Can Replicate
To maximize this entire architecture and ensure that Africa benefits gigantically before the total $9.3 trillion lifetime valuation of its 125 billion barrels depletes over the next 50 years, the continent must implement the structural blueprints of global energy powers:
- The Saudi Arabia Model (Phased Nationalization): Africa should move away from open-ended concession agreements. Following Saudi Arabia’s transition with Aramco, African parliaments can legally mandate rolling equity buyouts, transitioning foreign monopolies into technical service partners while keeping majority ownership and resources in public hands.
- The Norway Model (Strict Local Content Laws & Strategic SWFs): By mimicking Norway’s Equinor playbook, local content laws must make it illegal to import standard oilfield supplies. Every pipeline build, valve turn, and maritime vessel should utilize local African suppliers. Furthermore, surplus revenues must be locked in a Sovereign Wealth Fund separated from political budgets to build future-proof infrastructure.
- The UAE Model (Forced Industrial Diversification): Just as Dubai and Abu Dhabi used transient oil income to construct world-class aviation, trade, and financial hubs, Africa must treat oil as a temporary fuel. The capital retained from local refining must be intentionally redirected into non-oil secondary sectors—mechanized agriculture, local technological grids, and domestic manufacturing.
Conclusion: The Fire Within
The days of exporting Africa’s blood to buy back its sweat must come to an end. The continent can no longer afford to be the wealthy beggar sitting on a golden bench.
By aggressively updating our refineries, embracing private sector efficiency, enforcing strict environmental standards, training our youth, and trading directly with one another through the AfCFTA, Africa can finally close the loop of exploitation. Let us remember the final, guiding truth: “No matter how long the night, the dawn will surely break.” The dawn of Africa’s energy independence is no longer a distant dream—it is an industrial reality waiting to be claimed.

No Comments
Join the DiscussionBe the first to join the discussion!