At 7:14 a.m. on a Tuesday in Lagos, a notification arrives on Ola Oyetayo's phone. A client in Kigali has just confirmed receipt of a supplier payment sent from Accra the night before. Settlement time: eleven hours. Three years ago, the same transaction would have taken four days, routed through correspondent banks in Europe, converted twice through US dollars, and cost 11 per cent in fees and spreads. Today it moves on new rails, costs 2.8 per cent, and settles in local currency. Oyetayo screenshots the confirmation and sends it to the Verto team channel with a single word: "Progress."
This is not scale yet. But it is direction.
Young founders building cross-border market infrastructure across Africa operate in an environment where moving money, goods, or data between neighbouring countries often costs more and takes longer than transfers to Europe or North America. The cost of sending remittances within the continent averages 8.78 per cent of the transaction value—the highest of any global region—compared with a global average of 6.62 per cent and 4.80 per cent in South Asia, the lowest-cost region (Source: World Bank, Remittance Prices Worldwide, Q1 2025). Banks remain the most expensive channel, charging an average of 14.55 per cent. For businesses attempting to scale across borders, these friction costs accumulate quickly.
The African Development Bank's 2025 Trade Finance Report quantified the liquidity constraint: a US$74 billion trade finance gap, representing 5.4 per cent of the continent's total merchandise trade in 2024 (Source: AfDB 2025 Trade Finance Report). Commercial banks now handle only 23 per cent of Africa's total trade, down from 40 per cent between 2011 and 2019. The retreat of traditional bank intermediation has created both a vacuum and an opening for founder-led technology infrastructure.
Meanwhile, cross-border payments inside Africa remain heavily dollarized. Transactions between African currencies rarely settle directly; instead, they route through USD pairs, introducing conversion costs, reserve pressure, and delays even when the underlying trade is entirely regional (Source: TechTrendsKE, February 2026).
This is the operating terrain for a generation of founders whose companies depend on frictionless movement across borders—and who build the tools to reduce that friction for others.
Ola Oyetayo, Verto: Moving money faster than the system was built for
Ola Oyetayo built Verto to solve a problem he encountered repeatedly in Nigerian business: moving money to suppliers and partners across Africa was slower, more expensive, and less transparent than sending it to Europe. Verto is a B2B cross-border payments platform designed for fast-growing businesses that need predictable settlement windows and transparent pricing across African and global corridors (Source: Baobab Network fintech founder list, 2025).
The company operates across multiple African markets and international corridors, handling payments for businesses whose margins cannot absorb double-digit transaction fees or multi-day settlement delays. The core pitch is operational: replace opaque correspondent banking chains with direct settlement infrastructure that moves money in hours, not days, and prices risk transparently upfront.
What blocks Verto at each border is licensing fragmentation. A payment license in Nigeria does not grant operating authority in Kenya. Authorization in Ghana requires a separate application in Rwanda. Each new country means fresh compliance frameworks, new capital requirements, and months of regulatory engagement (Source: FinHive Africa Regulation Guide, June 2026). Oyetayo has described the operational friction plainly: African businesses often find it easier to move money to London than to neighbouring African countries, not because of distance or demand, but because payment infrastructure remains disconnected and compliance processes remain siloed (Source: Africa Briefing, payment barriers analysis).
Verto's traction is visible in its partnerships and geographic reach, though specific transaction volumes and licensing details were not available in public reporting. The company has raised venture capital and operates payment infrastructure that serves businesses expanding across Africa and into global markets.
If mutual recognition of payment licenses became enforceable across all African Union member states tomorrow—a true fintech passport—Oyetako's operational model would shift immediately. Engineering, compliance, and customer acquisition resources currently scattered across parallel licensing processes could consolidate. Time to market would compress. Capital efficiency would improve.
Oyetayo's advice to a 20-year-old in Accra, inferred from his public commentary and operating model: build for a problem you encounter yourself, in a market you understand operationally. Do not wait for perfect policy. Perfect policy will arrive years after the market moves. Understand the regulatory requirements in your first two markets better than the regulators do, and build relationships with central banks early—they move slowly, but they move, and they prefer to regulate entities they have watched operate responsibly.
Paul Akolade, Vant: Building the rails African small businesses can export on
Paul Akolade co-founded Vant to address a structural gap: African small businesses produce goods that have international demand, but most lack the infrastructure required to trade globally. Vant is a cross-border commerce platform that enables African small businesses to sell locally and globally through export-ready digital storefronts, embedded payments, and operational tools designed for scale (Source: ModelsSphere, January 2026).
"For many African entrepreneurs, the problem is not demand," Akolade has said. "From fashion and food to manufactured and creative products, demand exists well beyond local borders. Yet for most African entrepreneurs, international trade remains out of reach, not because of quality or ambition, but because the infrastructure required to trade globally has never been built with them in mind" (Source: ModelsSphere profile, January 2026).
Vant embeds payments, transaction records, and financial visibility directly into the commerce experience, giving small businesses the structure, credibility, and clarity required for cross-border trade. The platform lowers barriers to entry and formalizes commerce, helping transform local enterprises into globally competitive businesses while opening new markets for international buyers and partners.
The borders Vant crosses are operational and regulatory. Exporting from Nigeria to Europe or North America requires navigating customs documentation, payment settlement in multiple currencies, logistics coordination, and compliance with trade rules in each destination market. Many small businesses have the product but lack access to the systems that make export viable at scale. Vant provides the digital infrastructure layer—storefront, payments, records—that makes those systems accessible without requiring each business to build them independently.
What has been achieved: Vant operates across African markets and international trade corridors, serving small businesses whose products range from fashion to food to manufactured goods. Specific user numbers, transaction volumes, and revenue figures were not available in public reporting, but the company's partnerships and go-to-market positioning indicate traction with cross-border commerce operators.
If one rule changed tomorrow, Akolade's answer would likely focus on trade facilitation rather than payment licensing alone. Harmonized customs procedures under the African Continental Free Trade Area (AfCFTA), combined with simplified export documentation requirements, would accelerate the speed at which small businesses can formalize and scale international sales. The AfCFTA Digital Trade Protocol, stabilized in 2024, provides the legal framework for cross-border digital commerce, but implementation remains uneven (Source: AU Digital Trade Protocol; ResearchGate AfCFTA analysis).
Akolade's implicit advice, drawn from Vant's operating model: "Our goal is not to replace African entrepreneurs' ambition. African businesses are already capable. What they need is infrastructure that allows them to compete globally on equal footing" (Source: ModelsSphere profile). Build the boring, essential systems that others depend on. The work is not glamorous, but it is load-bearing.
Mark Afolabi, StableStack: Stablecoins as the layer under the payment
Mark Afolabi founded StableStack in 2025 to build the infrastructure that lets African fintechs move money as easily as messages—using stablecoins under the hood. StableStack's API connects local wallets, banks, and global payment networks so cross-border transfers settle in minutes instead of days (Source: TheCondia, 2025 fintech profiles).
The company operates at pre-seed stage and has partnered with Circle and other infrastructure providers to route USDC-based payouts. The technical model is straightforward: rather than converting currency mid-transaction through traditional correspondent banking rails, StableStack uses stablecoin settlement at endpoints, reducing both time and cost. The client-facing experience remains familiar—fiat in, fiat out—but the underlying movement happens on blockchain rails that settle faster and cheaper than legacy systems.
Afolabi's background includes a prior fintech build and exit, giving him operational credibility in a space crowded with first-time founders testing untested theses. StableStack's staying power, according to industry observers, lies in addressing a repeat, high-value problem—cross-border settlement—with clean execution and partnerships that provide regulatory and technical legitimacy (Source: TheCondia analysis).
What blocks StableStack at borders is both regulatory and infrastructural. Stablecoin regulation across Africa remains fragmented. Some jurisdictions have issued explicit guidance; others operate in grey zones where the legal status of digital assets remains undefined. The FinHive Africa Regulation Guide notes that fintech regulation changed faster in the 18 months through mid-2026 than in the previous five years, but it changed unevenly, and crypto rules vary widely by country (Source: FinHive Africa Regulation Guide, June 2026).
Currency on- and off-ramps—the points where users convert local fiat to stablecoins and back—require partnerships with licensed exchanges, banks, or money service operators in each market. Building those relationships and maintaining compliance in each jurisdiction is resource-intensive. Licensing in Nigeria does not cover operations in Kenya; authorization in South Africa does not extend to Ghana.
What has been achieved: StableStack has secured partnerships with Circle, a major stablecoin issuer, and other infrastructure players. The company is live and processing transactions, though specific volumes, user counts, and licensing details were not available in public reporting.
If one rule changed tomorrow, the highest-impact shift for Afolabi would be regulatory clarity on stablecoin settlement across African Union member states. If stablecoins issued by regulated entities were recognized as a legal settlement instrument across borders, the need for redundant currency conversion would fall, liquidity would improve, and transaction costs would drop further. The AfCFTA Digital Trade Protocol includes provisions to develop an annex on cross-border digital payments, but that annex remains in draft (Source: AU Digital Trade Protocol, Article on Cross-Border Digital Payments).
Afolabi's model implies a broader thesis: the next generation of African payment infrastructure will be built on programmable money. Stablecoins are not the product—they are the rail. The question is not whether African economies will adopt them, but whether African founders will build the layer that makes adoption seamless, compliant, and useful for everyday commerce.
Jumoke Dada, Taeillo: Moving furniture and African design across borders
Jumoke Dada founded Taeillo in 2018 as an online furniture platform offering Afro-inspired designs with augmented reality-enhanced shopping. The company has raised approximately $3 million across pre-seed and seed rounds, including a $2.5 million round in 2022 (Source: African Exponent, Top 10 E-Commerce Startups in Africa 2025).
Taeillo operates at the intersection of e-commerce, design, and cross-border logistics. The platform showcases African craftsmanship, connecting designers and manufacturers with buyers locally and internationally. Recently, it showcased at Lagos Design Week and is expanding into Kenya, promoting African design globally while building the operational infrastructure required to move physical goods across borders reliably.
What Taeillo solves is a supply chain and market access problem. African furniture makers and designers produce high-quality, culturally distinct products, but reaching international buyers requires navigating logistics, customs, payments, and marketing infrastructure that most small producers cannot afford to build independently. Taeillo provides the platform, the transaction layer, and the operational coordination that makes cross-border sales viable.
What stops Taeillo at each border is logistics fragmentation and the cost of moving goods. Unlike digital payments, which can settle on new rails like PAPSS, physical goods still require trucking, shipping, customs clearance, and last-mile delivery—all of which remain expensive and inconsistent across African markets. The $74 billion trade finance gap identified by the African Development Bank is partly a payment problem, but it is also a logistics and working capital problem (Source: AfDB 2025 Trade Finance Report). E-commerce growth in Nigeria and Kenya has repeatedly outpaced the logistics networks needed to support it, creating openings for founders who can stitch together last-mile delivery, warehousing, and working-capital financing into a single offering (Source: Nook Africa, Young Disruptors analysis).
What has been achieved: Taeillo has raised institutional funding, expanded into multiple markets, and built a recognizable brand at the intersection of African design and digital commerce. The company's use of augmented reality for furniture shopping is a differentiator in a category where visualizing products in context drives conversion. Specific revenue, user numbers, and logistics partnerships were not detailed in public reporting.
If one rule changed tomorrow, the highest-impact shift for Dada would be harmonized customs procedures under AfCFTA. Simplified, digitized customs clearance across African borders would reduce delays, lower costs, and make cross-border movement of goods as predictable as domestic shipping. The AfCFTA framework provides for preferential trade treatment, but operational implementation—particularly for small and medium enterprises—remains limited and mostly associated with the Guided Trade Initiative (Source: AfDB Trade Finance Report).
Dada's advice, inferred from Taeillo's trajectory: build a business that works in your home market first, then expand deliberately. Cross-border commerce is harder than it looks. Logistics, payments, and regulatory compliance all compound when you add a second country. But once the infrastructure is in place, the marginal cost of adding a third and fourth market falls. The unit economics are harder than pure-play fintech, but the addressable markets are larger and the competitive moats, once established, are more durable (Source: Nook Africa analysis).
What would let them scale, and who must act
The infrastructure layer is improving. The Pan-African Payment and Settlement System (PAPSS), launched in January 2024 by Afreximbank and the African Union, had connected more than 115 commercial banks by May 2024, with an equivalent number in the pipeline (Source: FXC Intel, March 2025). By September 2026, PAPSS reported strong growth in payment volumes and values as it entered its next strategic phase (Source: Afreximbank, September 2026). Kenya's KCB Group and Rwanda's Bank of Kigali both went live on PAPSS, enabling customers to send and receive cross-border payments in near-real time using local currencies.
This is infrastructure that founder-led platforms can build on. PAPSS provides instant or near-instant settlement without routing through offshore correspondent banks or dollar conversion. As adoption deepens among commercial banks, the cost and time advantages compound for platforms like Verto, StableStack, and any fintech routing business payments across African borders.
The AfCFTA Digital Trade Protocol, stabilized in 2024 and refined through 2025, includes provisions for cross-border digital payments and lays groundwork for harmonized digital trade rules (Source: AU Digital Trade Protocol; ResearchGate AfCFTA analysis). An annex on cross-border digital payments is under development. Implementation remains uneven, but the legal architecture is now in place.
Fintech passports—regulatory instruments that allow companies licensed in one jurisdiction to operate in others without restarting the licensing process—are emerging at the regional level. Ghana and Nigeria now recognize each other's fintech licenses. The East African Community is drafting a framework for a digital payment passport covering mobile money and payment initiation services. Under COMESA, which spans 21 countries, discussions on licensing reciprocity for payment service providers are ongoing (Source: Connecting Africa, fintech passport briefing). None of these frameworks is yet universal, but the direction is clear.
Who must act: central banks and regional economic communities must accelerate mutual recognition of fintech licenses. The technical and legal templates exist. What is missing is political coordination and the will to implement reciprocity at scale. The African Union has the convening authority; Afreximbank and the African Development Bank have the technical capacity and financing instruments. The bottleneck is not ideas—it is execution.
For founders, the path forward is operational. Build for the infrastructure that exists today, not the infrastructure you wish existed. PAPSS is live; integrate it. Stablecoin rails are faster and cheaper than correspondent banking; use them where regulation permits. Licensing takes twice as long as planned; start earlier, budget for it, and build relationships with regulators before you need approvals.
The continent does not need another remittance app. It needs founders who will build the boring, essential, cross-border infrastructure that makes a single market possible: invoicing systems that work in twelve currencies, compliance APIs that speak to fifteen central banks, settlement networks that clear payments while businesses sleep, logistics platforms that move goods as predictably as data.
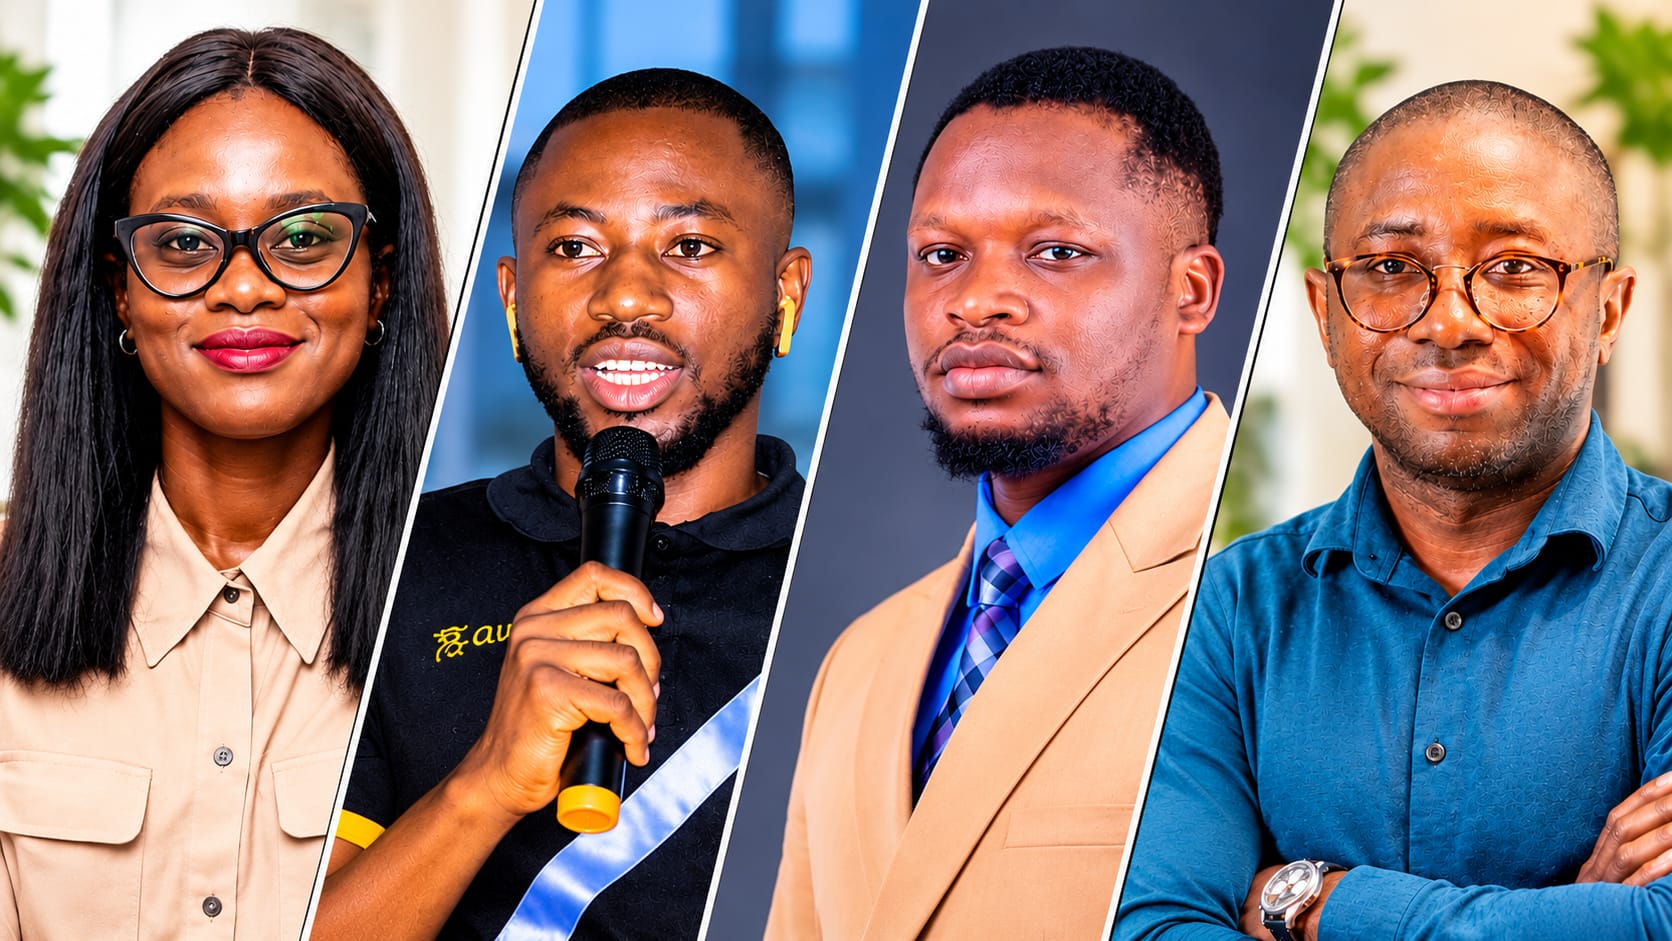
That work is not glamorous. But it is load-bearing. And the founders doing it now—Oyetayo, Akolade, Afolabi, Dada, and others building in the same direction—will define how the next twenty years of African commerce operate.
The technology exists. The capital is ready. Regulation and settlement infrastructure continue to decide which African trades survive and which quietly fall apart. What is changing—slowly, unevenly, but unmistakably—is the number of people building solutions instead of waiting for someone else to build them.
Progress is not scale. But it is direction.

1 Comment
Join the Discussion[…] Young African Founders Building Cross-Border Markets […]